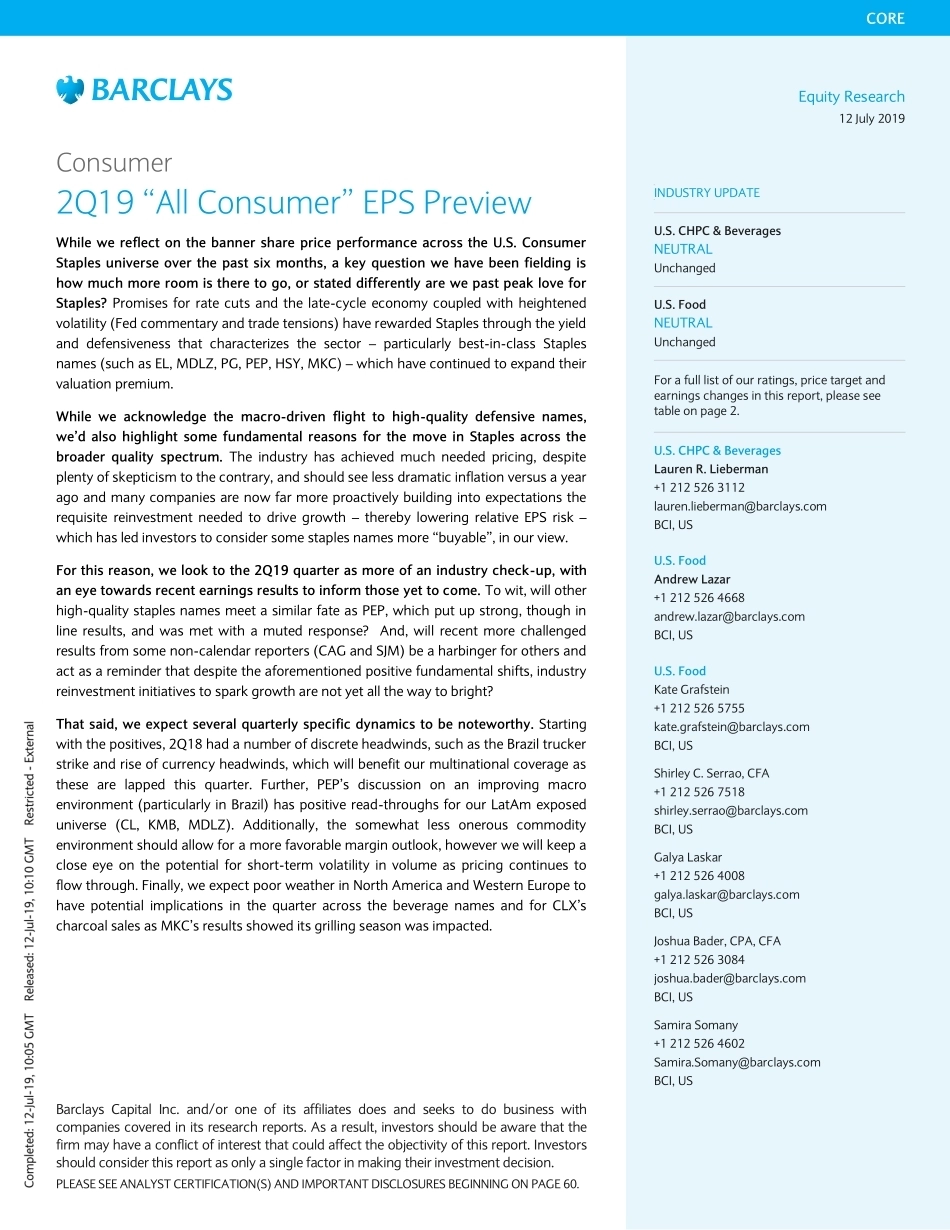
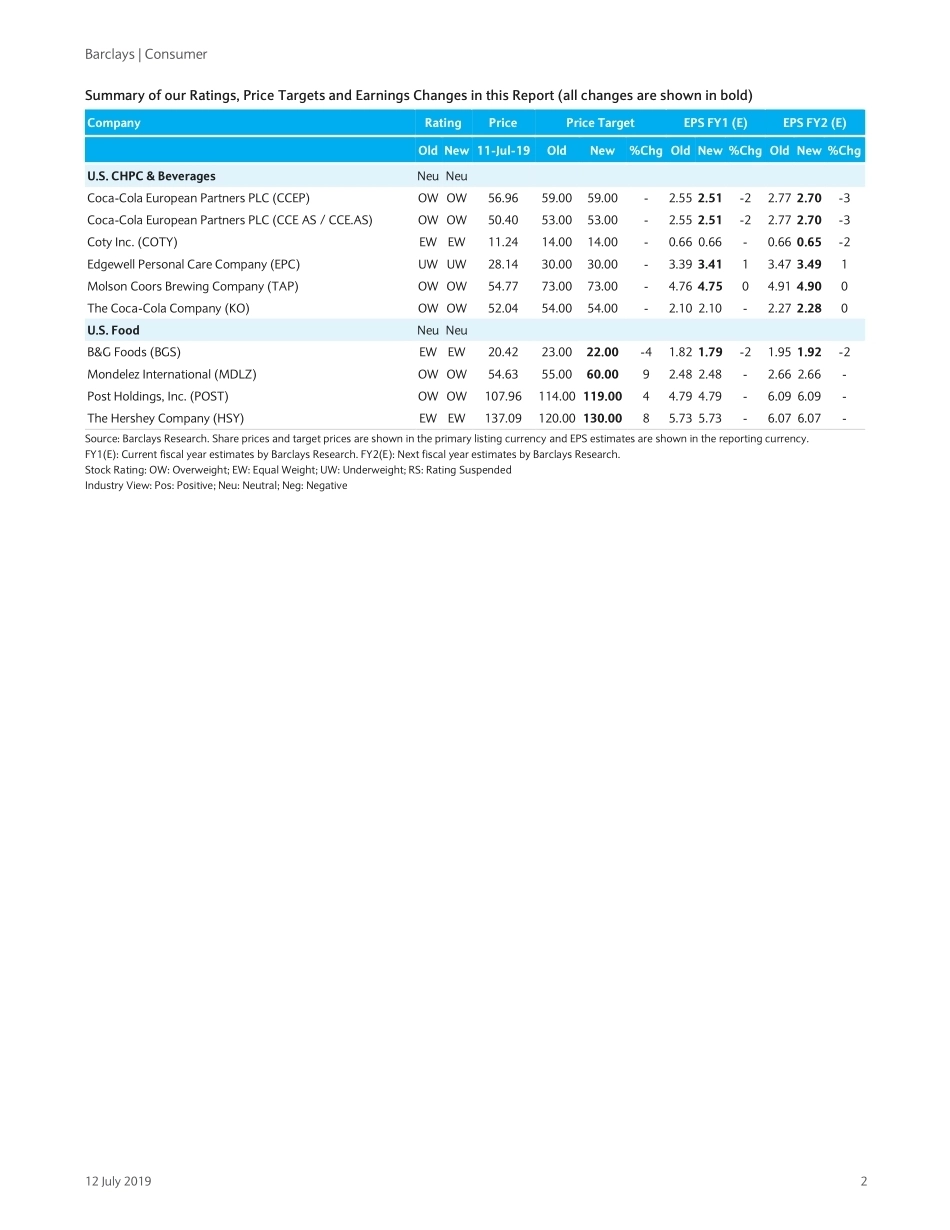
Equity Research 12 July 2019 CORE Barclays Capital Inc. and/or one of its affiliates does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. PLEASE SEE ANALYST CERTIFICATION(S) AND IMPORTANT DISCLOSURES BEGINNING ON PAGE 60. Restricted - Internal Consumer 2Q19 “All Consumer” EPS Preview While we reflect on the banner share price performance across the U.S. Consumer Staples universe over the past six months, a key question we have been fielding is how much more room is there to go, or stated differently are we past peak love for Staples? Promises for rate cuts and the late-cycle economy coupled with heightened volatility (Fed commentary and trade tensions) have rewarded Staples through the yield and defensiveness that characterizes the sector – particularly best-in-class Staples names (such as EL, MDLZ, PG, PEP, HSY, MKC) – which have continued to expand their valuation premium. While we acknowledge the macro-driven flight to high-quality defensive names, we’d also highlight some fundamental reasons for the move in Staples across the broader quality spectrum. The industry has achieved much needed pricing, despite plenty of skepticism to the contrary, and should see less dramatic inflation versus a year ago and many companies are now far more proactively building into expectations the requisite reinvestment needed to drive growth – thereby lowering relative EPS risk – which has led investors to consider some staples names more “buyable”, in our view. For this reason, we look to the 2Q19 quarter as more of an industry check-up, with an eye towards recent earnings results to inform those yet to come. To wit, will other high-quality staples names meet a similar fate as PEP, which put up strong, though in line results, and was met with a muted response? And, will recent more challenged results from some non-calendar reporters (CAG and SJM) be a harbinger for others and act as a reminder that despite the aforementioned positive fundamental shifts, industry reinvestment initiatives to spark growth are not yet all the way to bright? That said, we expect several quarterly specific dynamics to be noteworthy. Starting with the positives, 2Q18 had a number of discrete headwinds, such as the Brazil trucker strike and rise of currency headwinds, which will benefit our multinational coverage as these are lapped this quarter. Further, PEP’s discussion on an improving macro environment (particularly in Brazil) has positive read-throughs for our LatAm exposed universe (CL, KMB, MDLZ). Additionally, the somewhat less onerous commodity environment should allow for a more favorable margin outlook, however we will keep a close eye on the potential for short-term volatility in volume as pricing continues to flow through. Finally, we expect poor weather in North America and Western Europe to have potential implications in the quarter across the beverage names and for CLX’s charcoal sales as MKC’s results showed its grilling season was impacted. INDUSTRY UPDATE U.S. CHPC & Beverages NEUTRAL Unchanged U.S. Food NEUTRAL Unchanged For a full list of our ratings, price target and earnings changes in this report, please see table on page 2. U.S. CHPC & Beverages Lauren R. Lieberman +1 212 526 3112 lauren.lieberman@barclays.com BCI, US U.S. Food Andrew Lazar +1 212 526 4668 andrew.lazar@barclays.com BCI, US U.S. Food Kate Grafstein +1 212 526 5755 kate.grafstein@barclays.com BCI, US Shirley C. Serrao, CFA +1 212 526 7518 shirley.serrao@barclays.com BCI, US Galya Laskar +1 212 526 4008 galya.laskar@barclays.com BCI, US Joshua Bader, CPA, CFA +1 212 526 3084 joshua.bader@barclays.com BCI, US Samira Somany +1 212 526 4602 Samira.Somany@barclays.com BCI, US Barclays | Consumer 12 July 2019 2 Summary of our Ratings, Price Targets and Earnings Changes in this Report (all changes are shown in bold) Company Rating Price Price Target EPS FY1 (E) EPS FY2 (E) Old New 11-Jul-19 Old New %Chg Old New %Chg Old New %Chg U.S. CHPC & Beverages Neu Neu Coca-Cola European Partners PLC (CCEP) OW OW 56.96 59.00 59.00 - 2.55 2.51 -2 2.77 2.70 -3 Coca-Cola European Partners PLC (CCE AS / CCE.AS) OW OW 50.40 53.00 53.00 - 2.55 2.51 -2 2.77 2.70 -3 Coty Inc. (COTY) EW EW 11.24 14.00 14.00 - 0.66 0.66 - 0.66 0.65 -2 Edgewell Personal Care Company (EPC) UW UW 28.14 30.00 30.00 - 3.39 3.41 1 3.47 3.49 1 Molson Coors Brewing Company (TAP) OW OW 54.77 73.00 73.00 - 4.76 4.75 0 4.91 4.90 0 The Coca-Cola Company (KO) OW OW 52.04 54.00 54.00 - 2.10 2.10 - 2.27 2.28 0 U.S. Food Neu Neu B&G Foods (BGS) EW EW 20.42 23.00 22.00 -4 1.82 1.79 -2 1.95 1.92 -2 Mondelez International (MDLZ) OW OW 54.63 55.00 60.00 9 2.48 2.48 - 2.66 2.66 - Post Holdings, Inc. (POST) OW OW 107.96 114.00 119.00 4 4.79 4.79 - 6.09 6.09 - The Hershey...




发表评论取消回复