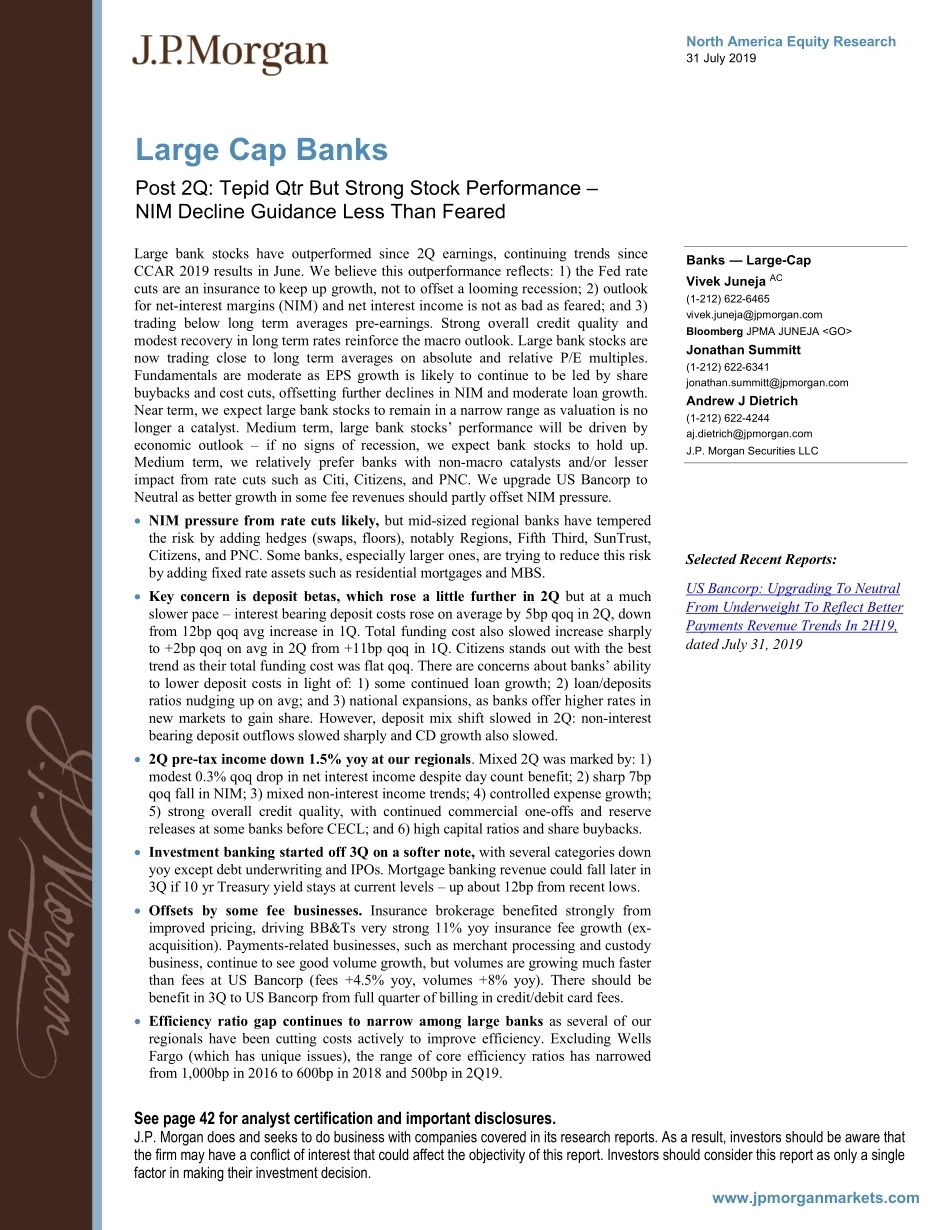
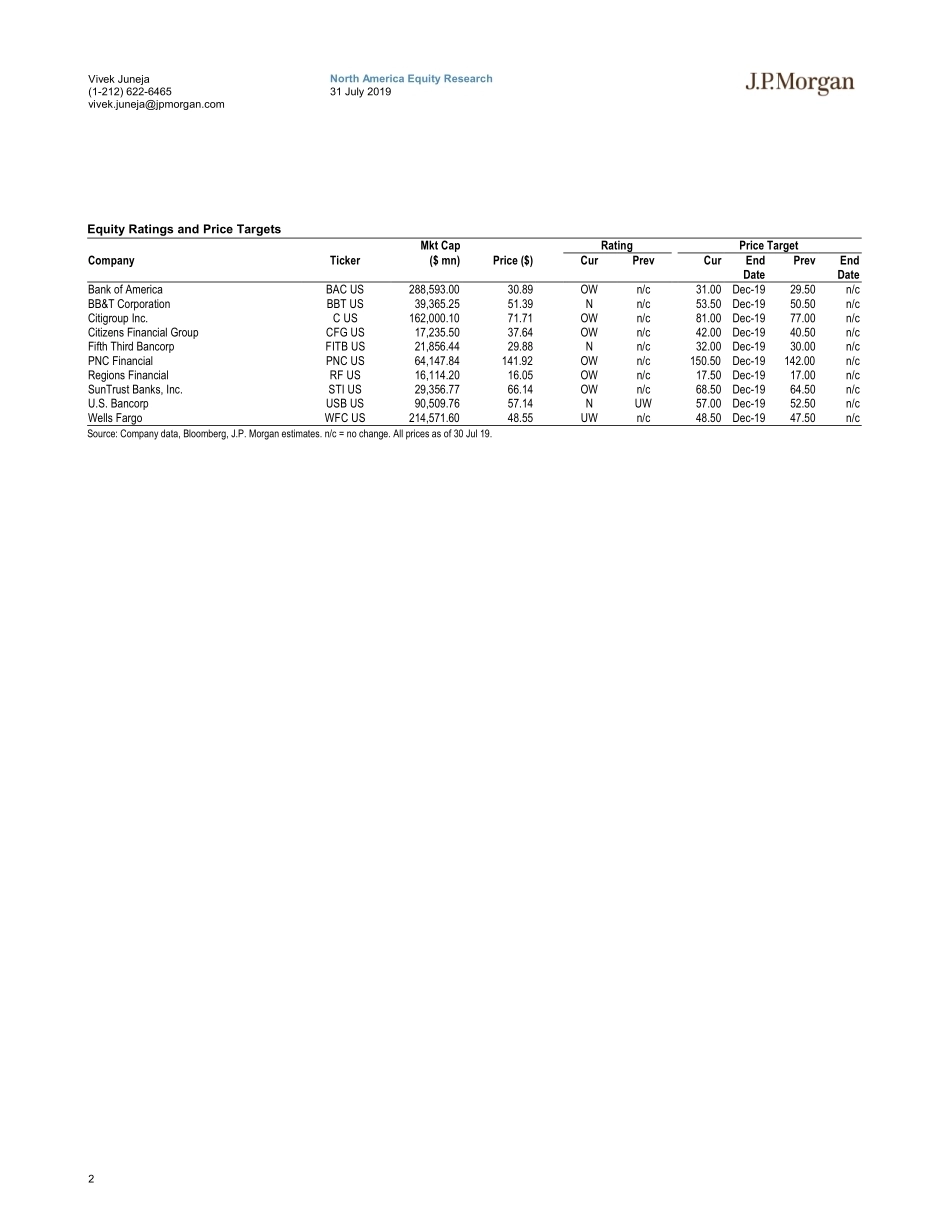
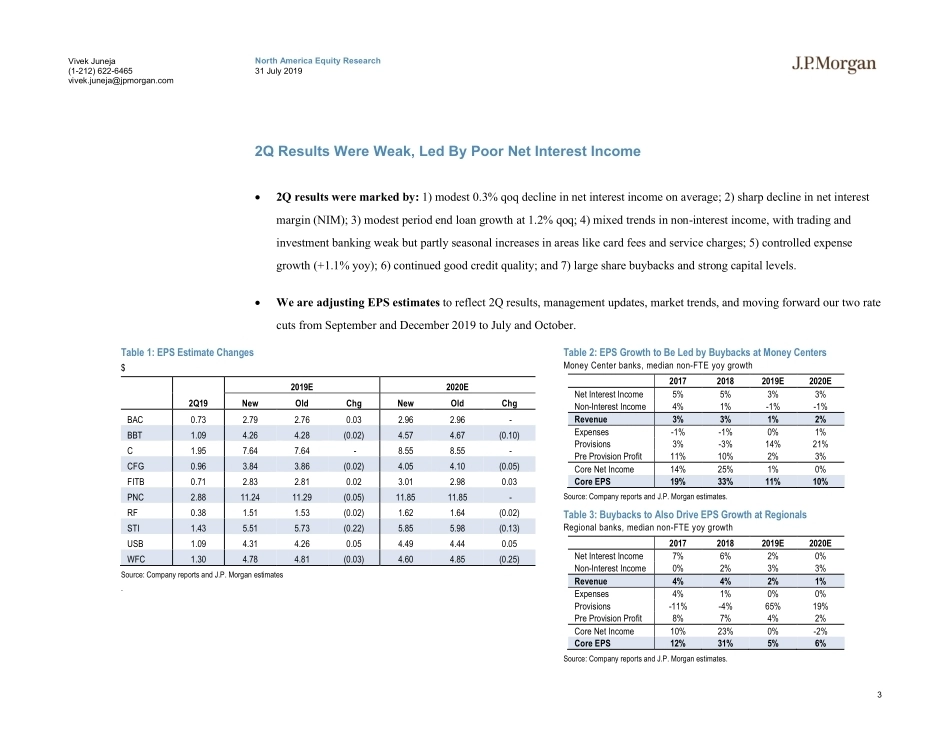
www.jpmorganmarkets.comNorth America Equity Research31 July 2019Large Cap BanksPost 2Q: Tepid Qtr But Strong Stock Performance –NIM Decline Guidance Less Than FearedBanks — Large-CapVivek Juneja AC(1-212) 622-6465vivek.juneja@jpmorgan.comBloomberg JPMA JUNEJA Jonathan Summitt(1-212) 622-6341jonathan.summitt@jpmorgan.comAndrew J Dietrich(1-212) 622-4244aj.dietrich@jpmorgan.comJ.P. Morgan Securities LLCSee page 42 for analyst certification and important disclosures.J.P. Morgan does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision.Large bank stocks have outperformed since 2Q earnings, continuing trends since CCAR 2019 results in June. We believe this outperformance reflects: 1) the Fed rate cuts are an insurance to keep up growth, not to offset a looming recession; 2) outlook for net-interest margins (NIM) and net interest income is not as bad as feared; and 3) trading below long term averages pre-earnings. Strong overall credit quality and modest recovery in long term rates reinforce the macro outlook. Large bank stocks are now trading close to long term averages on absolute and relative P/E multiples. Fundamentals are moderate as EPS growth is likely to continue to be led by share buybacks and cost cuts, offsetting further declines in NIM and moderate loan growth. Near term, we expect large bank stocks to remain in a narrow range as valuation is no longer a catalyst. Medium term, large bank stocks’ performance will be driven by economic outlook – if no signs of recession, we expect bank stocks to hold up. Medium term, we relatively prefer banks with non-macro catalysts and/or lesser impact from rate cuts such as Citi, Citizens, and PNC. We upgrade US Bancorp to Neutral as better growth in some fee revenues should partly offset NIM pressure. NIM pressure from rate cuts likely, but mid-sized regional banks have tempered the risk by adding hedges (swaps, floors), notably Regions, Fifth Third, SunTrust, Citizens, and PNC. Some banks, especially larger ones, are trying to reduce this risk by adding fixed rate assets such as residential mortgages and MBS. Key concern is deposit betas, which rose a little further in 2Q but at a much slower pace – interest bearing deposit costs rose on average by 5bp qoq in 2Q, down from 12bp qoq avg increase in 1Q. Total funding cost also slowed increase sharply to +2bp qoq on avg in 2Q from +11bp qoq in 1Q. Citizens stands out with the best trend as their total funding cost was flat qoq. There are concerns about banks’ ability to lower deposit costs in light of: 1) some continued loan growth; 2) loan/deposits ratios nudging up on avg; and 3) national expansions, as banks offer higher rates in new markets to gain share. However, deposit mix shift slowed in 2Q: non-interest bearing deposit outflows slowed sharply and CD growth also slowed. 2Q pre-tax income down 1.5% yoy at our regionals. Mixed 2Q was marked by: 1) modest 0.3% qoq drop in net interest income despite day count benefit; 2) sharp 7bp qoq fall in NIM; 3) mixed non-interest income trends; 4) controlled expense growth; 5) strong overall credit quality, with continued commercial one-offs and reserve releases at some banks before CECL; and 6) high capital ratios and share buybacks. Investment banking started off 3Q on a softer note, with several categories down yoy except debt underwriting and IPOs. Mortgage banking revenue could fall later in 3Q if 10 yr Treasury yield stays at current levels – up about 12bp from recent lows. Offsets by some fee businesses. Insurance brokerage benefited strongly from improved pricing, driving BB&Ts very strong 11% yoy insurance fee growth (ex-acquisition). Payments-related businesses, such as merchant processing and custody business, continue to see good volume growth, but volumes are growing much faster than fees at US Bancorp (fees +4.5% yoy, volumes +8% yoy). There should be benefit in 3Q to US Bancorp from full quarter of billing in credit/debit card fees. Efficiency ratio gap continues to narrow among large banks as several of our regionals have been cutting costs actively to improve efficiency. Excluding Wells Fargo (which has unique issues), the range of core efficiency ratios has narrowed from 1,000bp in 2016 to 600bp in 2018 and 500bp in 2Q19. Selected Recent Reports:US Bancorp: Upgrading To Neutral From Underweight To Reflect Better Payments Revenue Trends In 2H19,dated July 31, 20192North America Equity Research31 July 2019Vivek Juneja(1-212) 622-6465vivek.juneja@jpmorgan.comEquity Ratings and Price TargetsMkt CapRatingPrice TargetCompanyTicker($ mn)Price ($)CurPrevCurEnd DatePrevEnd DateBank of AmericaBAC US288,593.0030.89OWn/c31.00Dec-1929.50n/cBB&T CorporationBBT US39,365.2551.39Nn/c53.50Dec-1950.50n/cCitigroup ...




发表评论取消回复