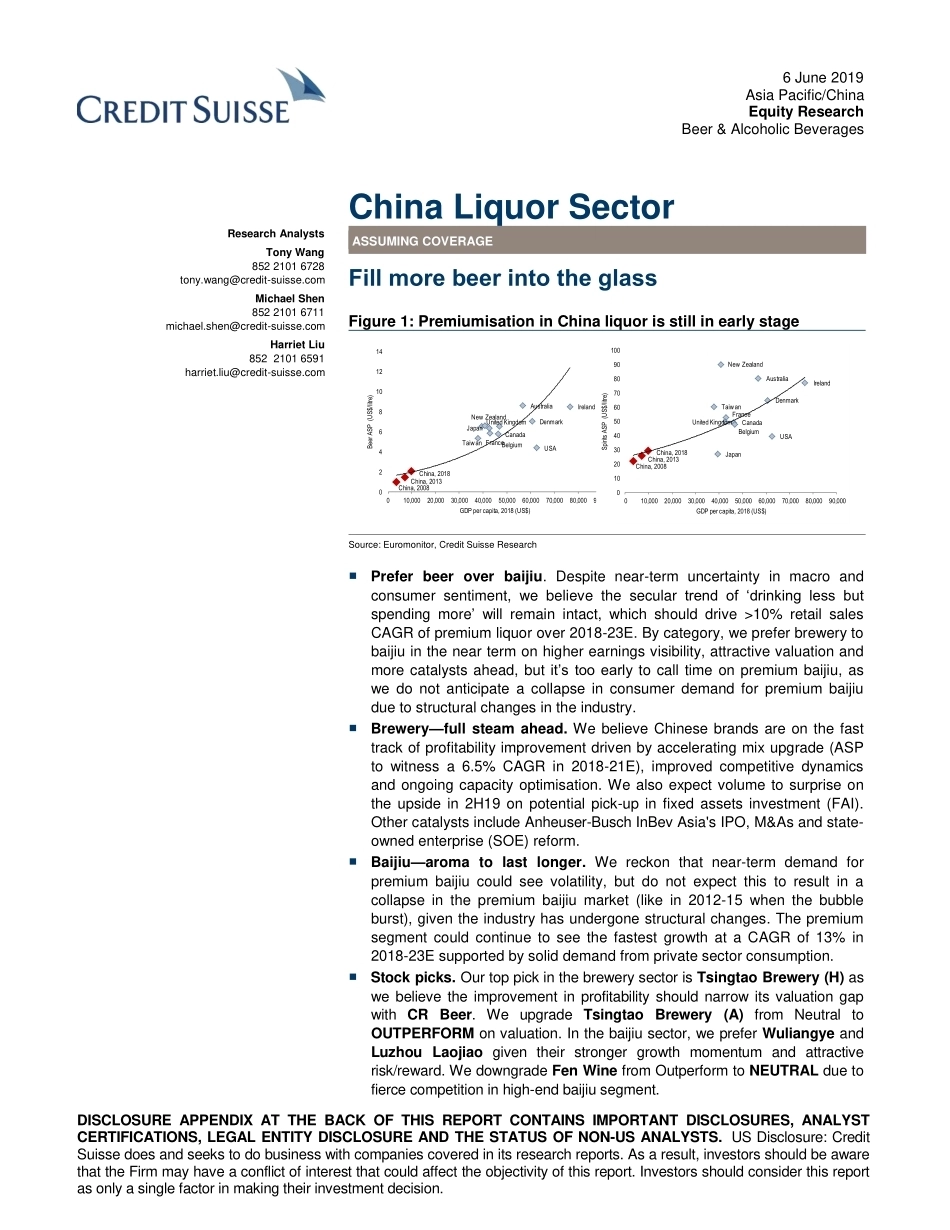
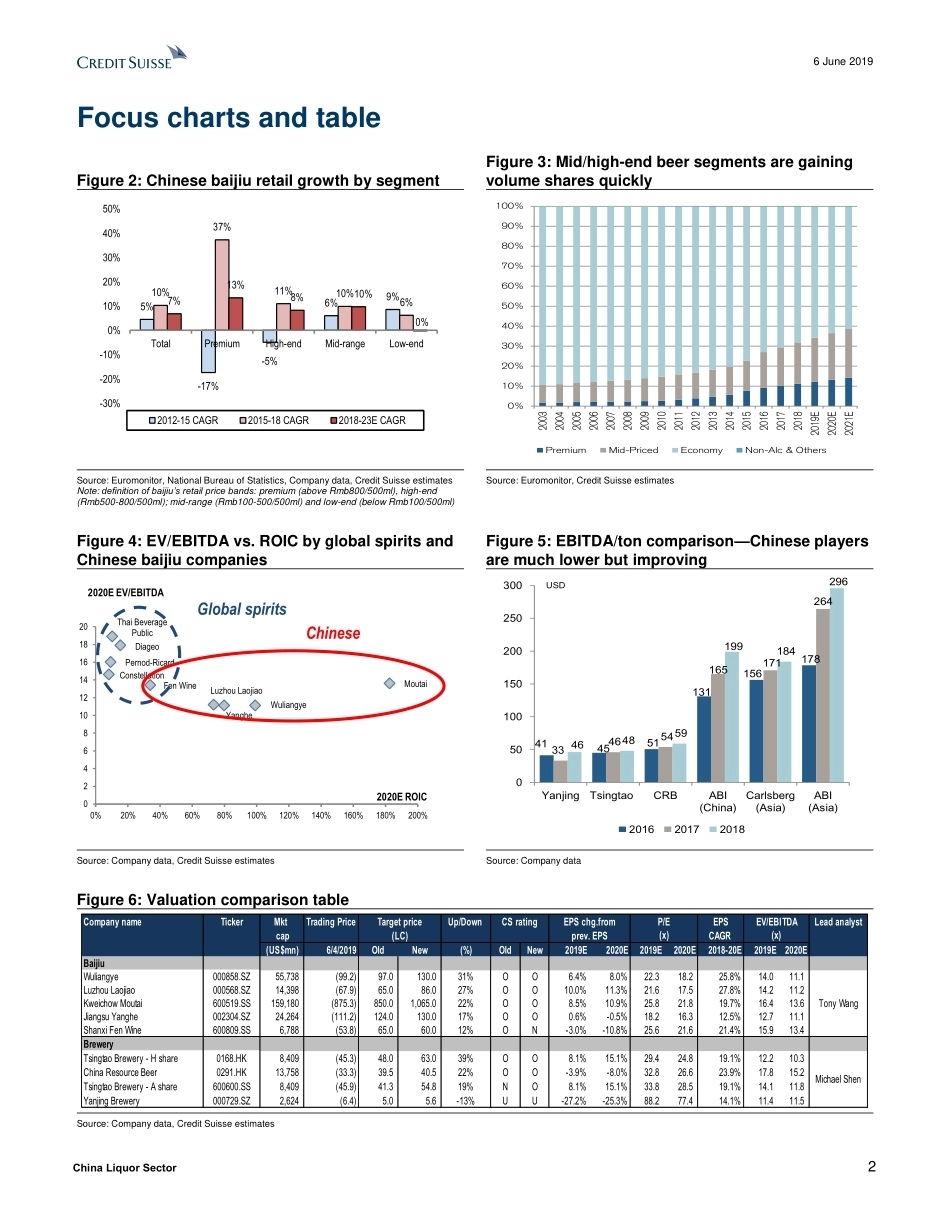
DISCLOSURE APPENDIX AT THE BACK OF THIS REPORT CONTAINS IMPORTANT DISCLOSURES, ANALYST CERTIFICATIONS, LEGAL ENTITY DISCLOSURE AND THE STATUS OF NON-US ANALYSTS. US Disclosure: Credit Suisse does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the Firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. 6 June 2019 Asia Pacific/China Equity Research Beer & Alcoholic Beverages China Liquor Sector Research Analysts Tony Wang 852 2101 6728 tony.wang@credit-suisse.com Michael Shen 852 2101 6711 michael.shen@credit-suisse.com Harriet Liu 852 2101 6591 harriet.liu@credit-suisse.com ASSUMING COVERAGE Fill more beer into the glass Figure 1: Premiumisation in China liquor is still in early stage Source: Euromonitor, Credit Suisse Research ■ Prefer beer over baijiu. Despite near-term uncertainty in macro and consumer sentiment, we believe the secular trend of ‘drinking less but spending more’ will remain intact, which should drive >10% retail sales CAGR of premium liquor over 2018-23E. By category, we prefer brewery to baijiu in the near term on higher earnings visibility, attractive valuation and more catalysts ahead, but it’s too early to call time on premium baijiu, as we do not anticipate a collapse in consumer demand for premium baijiu due to structural changes in the industry. ■ Brewery—full steam ahead. We believe Chinese brands are on the fast track of profitability improvement driven by accelerating mix upgrade (ASP to witness a 6.5% CAGR in 2018-21E), improved competitive dynamics and ongoing capacity optimisation. We also expect volume to surprise on the upside in 2H19 on potential pick-up in fixed assets investment (FAI). Other catalysts include Anheuser-Busch InBev Asia's IPO, M&As and state-owned enterprise (SOE) reform. ■ Baijiu—aroma to last longer. We reckon that near-term demand for premium baijiu could see volatility, but do not expect this to result in a collapse in the premium baijiu market (like in 2012-15 when the bubble burst), given the industry has undergone structural changes. The premium segment could continue to see the fastest growth at a CAGR of 13% in 2018-23E supported by solid demand from private sector consumption. ■ Stock picks. Our top pick in the brewery sector is Tsingtao Brewery (H) as we believe the improvement in profitability should narrow its valuation gap with CR Beer. We upgrade Tsingtao Brewery (A) from Neutral to OUTPERFORM on valuation. In the baijiu sector, we prefer Wuliangye and Luzhou Laojiao given their stronger growth momentum and attractive risk/reward. We downgrade Fen Wine from Outperform to NEUTRAL due to fierce competition in high-end baijiu segment. China, 2008China, 2013China, 2018JapanTaiwanAustraliaNew ZealandCanadaUSABelgiumDenmarkFranceIrelandUnited Kingdom02468101214010,00020,00030,00040,00050,00060,00070,00080,00090,000Beer ASP (US$/litre)GDP per capita, 2018 (US$)China, 2008China, 2013China, 2018JapanTaiwanAustraliaNew ZealandCanadaUSABelgiumDenmarkFranceIrelandUnited Kingdom0102030405060708090100010,00020,00030,00040,00050,00060,00070,00080,00090,000Spirits ASP (US$/litre)GDP per capita, 2018 (US$) 6 June 2019 China Liquor Sector 2 Focus charts and table Figure 2: Chinese baijiu retail growth by segment Figure 3: Mid/high-end beer segments are gaining volume shares quickly Source: Euromonitor, National Bureau of Statistics, Company data, Credit Suisse estimates Note: definition of baijiu’s retail price bands: premium (above Rmb800/500ml), high-end (Rmb500-800/500ml); mid-range (Rmb100-500/500ml) and low-end (below Rmb100/500ml) Source: Euromonitor, Credit Suisse estimates Figure 4: EV/EBITDA vs. ROIC by global spirits and Chinese baijiu companies Figure 5: EBITDA/ton comparison—Chinese players are much lower but improving Source: Company data, Credit Suisse estimates Source: Company data Figure 6: Valuation comparison table Source: Company data, Credit Suisse estimates 5% -17% -5% 6% 9% 10% 37% 11% 10% 6% 7% 13% 8% 10% 0% -30%-20%-10%0%10%20%30%40%50%TotalPremiumHigh-endMid-rangeLow-end2012-15 CAGR2015-18 CAGR2018-23E CAGR0%10%20%30%40%50%60%70%80%90%100%20032004200520062007200820092010201120122013201420152016201720182019E2020E2021EPremiumMid-PricedEconomyNon-Alc & OthersMoutai Wuliangye Yanghe Luzhou Laojiao Fen Wine Diageo Pernod-Ricard Constellation Thai Beverage Public 024681012141618200%20%40%60%80%100%120%140%160%180%200%2020E ROIC 2020E EV/EBITDA Chinese Global spirits 41 45 51 131 156 178 33 46 54 165 171 264 46 48 59 199 184 296 050100150200250300YanjingTsingtaoCRBABI(China)Carlsberg(Asia)ABI(Asia)201620172018USDCompany nameMkt Trading PriceUp/Down EPS Lead analyst capCAGR (US$mn)6/4/2019OldNew(%)OldNew2019E2020E2019E2020E2018-20E2019E2020EBaijiuWuliangye000858.SZ55,738 (99.2) 97.0 130.0 31%OO6.4%8.0%22.3 18.2 25.8%14.0 11.1 Luzhou Laojiao000568...




发表评论取消回复