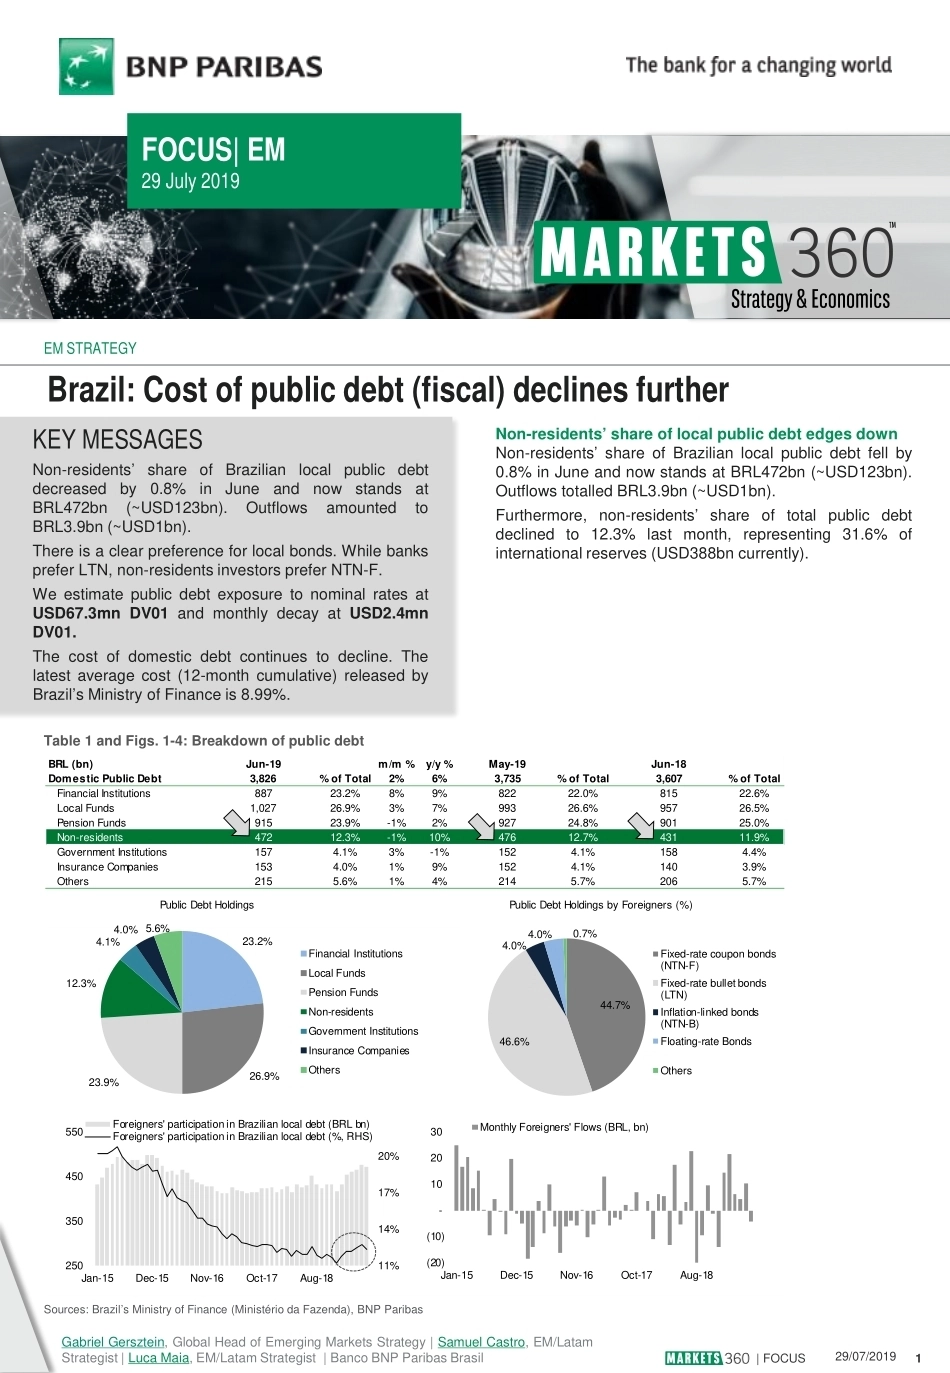
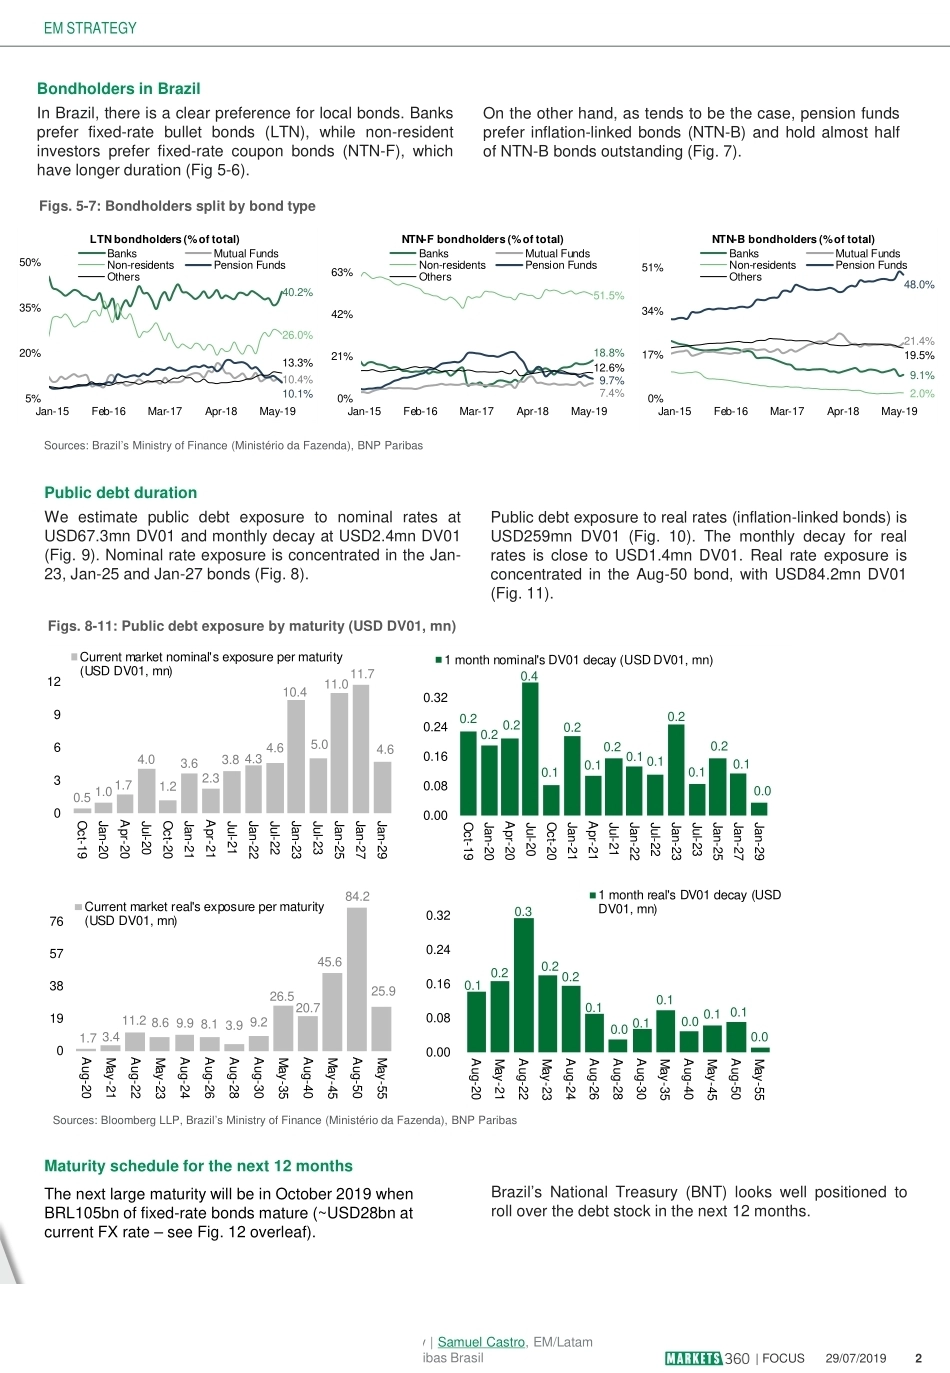
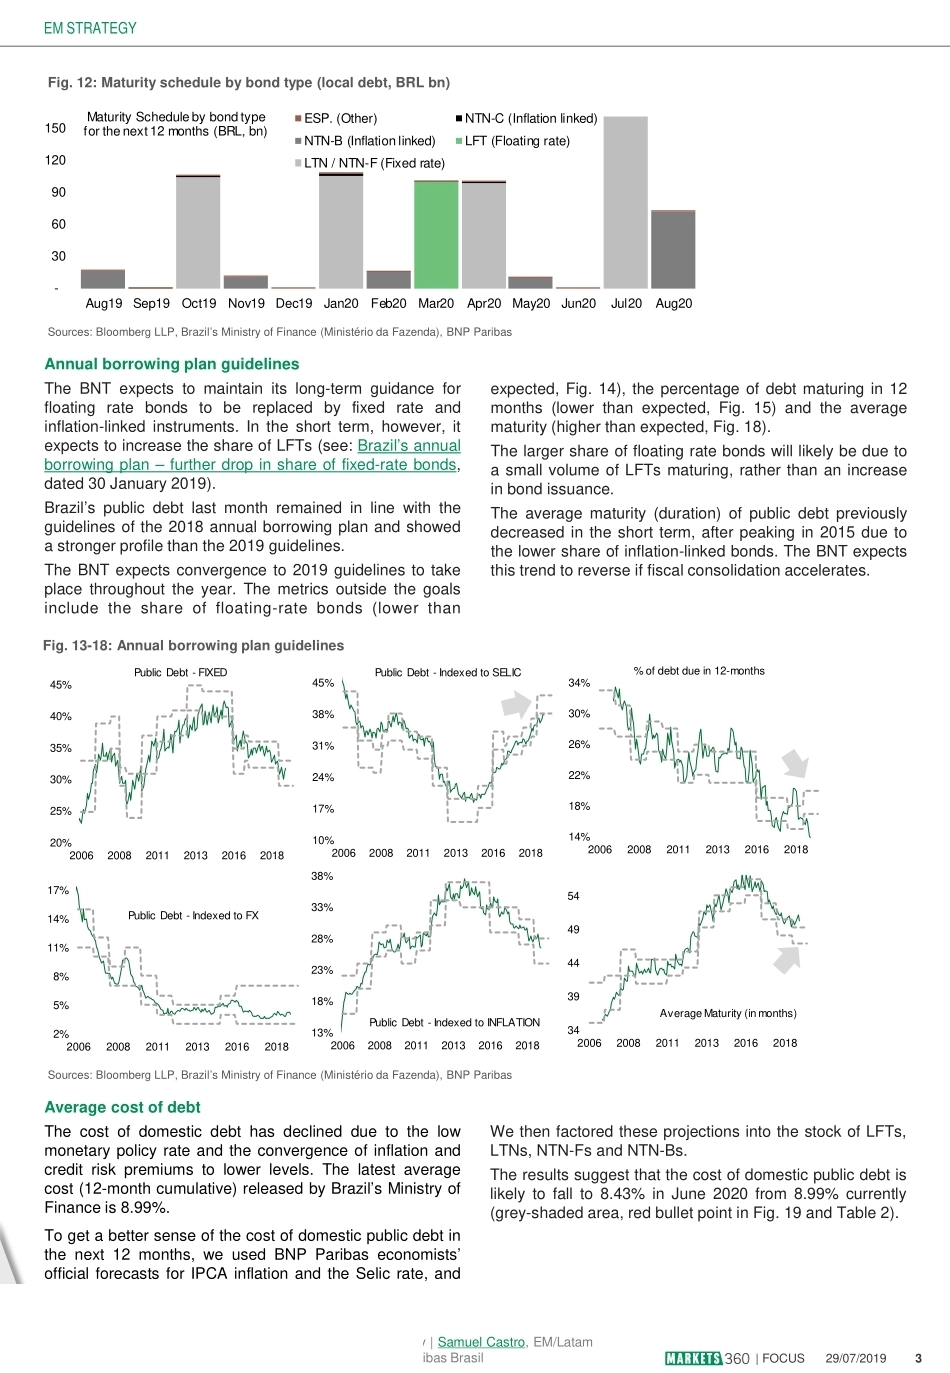
| FOCUS 29/07/2019 1 FOCUS| EM 29 July 2019 Brazil: Cost of public debt (fiscal) declines further KEY MESSAGES Non-residents’ share of Brazilian local public debt decreased by 0.8% in June and now stands at BRL472bn (~USD123bn). Outflows amounted to BRL3.9bn (~USD1bn). There is a clear preference for local bonds. While banks prefer LTN, non-residents investors prefer NTN-F. We estimate public debt exposure to nominal rates at USD67.3mn DV01 and monthly decay at USD2.4mn DV01. The cost of domestic debt continues to decline. The latest average cost (12-month cumulative) released by Brazil’s Ministry of Finance is 8.99%. EM STRATEGY Non-residents’ share of local public debt edges down Non-residents’ share of Brazilian local public debt fell by 0.8% in June and now stands at BRL472bn (~USD123bn). Outflows totalled BRL3.9bn (~USD1bn). Furthermore, non-residents’ share of total public debt declined to 12.3% last month, representing 31.6% of international reserves (USD388bn currently). Table 1 and Figs. 1-4: Breakdown of public debt Sources: Brazil’s Ministry of Finance (Ministério da Fazenda), BNP Paribas BRL (bn)Jun-19m/m %y/y %May-19Jun-18Domestic Public Debt3,826% of Total2%6%3,735% of Total3,607% of TotalFinancial Institutions88723.2%8%9%82222.0%81522.6%Local Funds1,02726.9%3%7%99326.6%95726.5%Pension Funds91523.9%-1%2%92724.8%90125.0%Non-residents47212.3%-1%10%47612.7%43111.9%Government Institutions1574.1%3%-1%1524.1%1584.4%Insurance Companies1534.0%1%9%1524.1%1403.9%Others2155.6%1%4%2145.7%2065.7%Public Debt HoldingsPublic Debt Holdings by Foreigners (%)44.7%46.6%4.0%4.0%0.7%Fixed-rate coupon bonds(NTN-F)Fixed-rate bullet bonds(LTN)Inflation-linked bonds(NTN-B)Floating-rate BondsOthers23.2%26.9%23.9%12.3%4.1%4.0% 5.6%Financial InstitutionsLocal FundsPension FundsNon-residentsGovernment InstitutionsInsurance CompaniesOthers11%14%17%20% 250 350 450 550Jan-15Dec-15Nov-16Oct-17Aug-18Foreigners' participation in Brazilian local debt (BRL bn)Foreigners' participation in Brazilian local debt (%, RHS) (20) (10) - 10 20 30Jan-15Dec-15Nov-16Oct-17Aug-18Monthly Foreigners' Flows (BRL, bn)Gabriel Gersztein, Global Head of Emerging Markets Strategy | Samuel Castro, EM/Latam Strategist | Luca Maia, EM/Latam Strategist | Banco BNP Paribas Brasil | FOCUS 29/07/2019 2 EM STRATEGY Public debt duration We estimate public debt exposure to nominal rates at USD67.3mn DV01 and monthly decay at USD2.4mn DV01 (Fig. 9). Nominal rate exposure is concentrated in the Jan-23, Jan-25 and Jan-27 bonds (Fig. 8). Public debt exposure to real rates (inflation-linked bonds) is USD259mn DV01 (Fig. 10). The monthly decay for real rates is close to USD1.4mn DV01. Real rate exposure is concentrated in the Aug-50 bond, with USD84.2mn DV01 (Fig. 11). Figs. 8-11: Public debt exposure by maturity (USD DV01, mn) Sources: Bloomberg LLP, Brazil’s Ministry of Finance (Ministério da Fazenda), BNP Paribas Maturity schedule for the next 12 months The next large maturity will be in October 2019 when BRL105bn of fixed-rate bonds mature (~USD28bn at current FX rate – see Fig. 12 overleaf). Brazil’s National Treasury (BNT) looks well positioned to roll over the debt stock in the next 12 months. Bondholders in Brazil In Brazil, there is a clear preference for local bonds. Banks prefer fixed-rate bullet bonds (LTN), while non-resident investors prefer fixed-rate coupon bonds (NTN-F), which have longer duration (Fig 5-6). On the other hand, as tends to be the case, pension funds prefer inflation-linked bonds (NTN-B) and hold almost half of NTN-B bonds outstanding (Fig. 7). Figs. 5-7: Bondholders split by bond type Sources: Brazil’s Ministry of Finance (Ministério da Fazenda), BNP Paribas 40.2%10.4%26.0%10.1%13.3%5%20%35%50%Jan-15Feb-16Mar-17Apr-18May-19BanksMutual FundsNon-residentsPension FundsOthersLTN bondholders (% of total)9.1%21.4%2.0%48.0%19.5%0%17%34%51%Jan-15Feb-16Mar-17Apr-18May-19BanksMutual FundsNon-residentsPension FundsOthersNTN-B bondholders (% of total)18.8%7.4%51.5%9.7%12.6%0%21%42%63%Jan-15Feb-16Mar-17Apr-18May-19BanksMutual FundsNon-residentsPension FundsOthersNTN-F bondholders (% of total)Gabriel Gersztein, Global Head of Emerging Markets Strategy | Samuel Castro, EM/Latam Strategist | Luca Maia, EM/Latam Strategist | Banco BNP Paribas Brasil 0.5 1.0 1.74.01.23.62.33.8 4.34.610.45.011.011.74.6036912Oct-19Jan-20Apr-20Jul-20Oct-20Jan-21Apr-21Jul-21Jan-22Jul-22Jan-23Jul-23Jan-25Jan-27Jan-29Current market nominal's exposure per maturity(USD DV01, mn)0.20.2 0.20.40.10.20.10.2 0.1 0.10.20.10.20.10.00.000.080.160.240.32Oct-19Jan-20Apr-20Jul-20Oct-20Jan-21Apr-21Jul-21Jan-22Jul-22Jan-23Jul-23Jan-25Jan-27Jan-291 month nominal's DV01 decay (USD DV01, mn)1.7 3.411.2 8.6 9.9 8.1 3.9 9.226.520.745.684.225.9019385776Aug-20May-21Aug-22May-23Aug-24Aug-26Aug-28Aug-30May-35Aug-40May-45Aug-50May-55Current market real's exposure per maturity(USD DV01, mn)0.10.20.30.20.20.10.0 0.10.10.0 0.1 0.10.00.000.080.160.240.32Aug-20May-21Aug-22May-23Aug-24Aug-26Aug-28Aug-30Ma...




发表评论取消回复