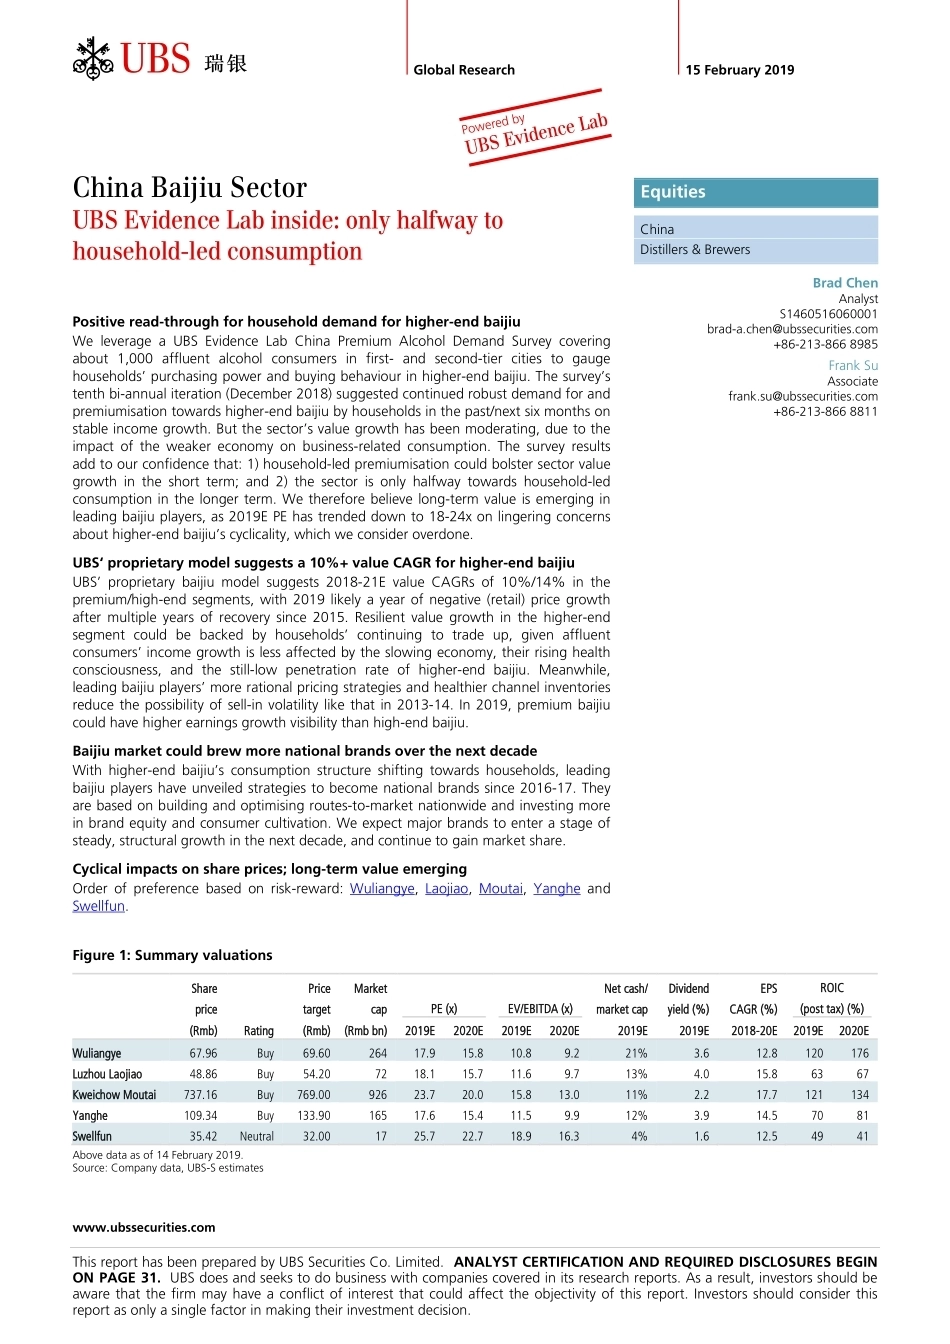
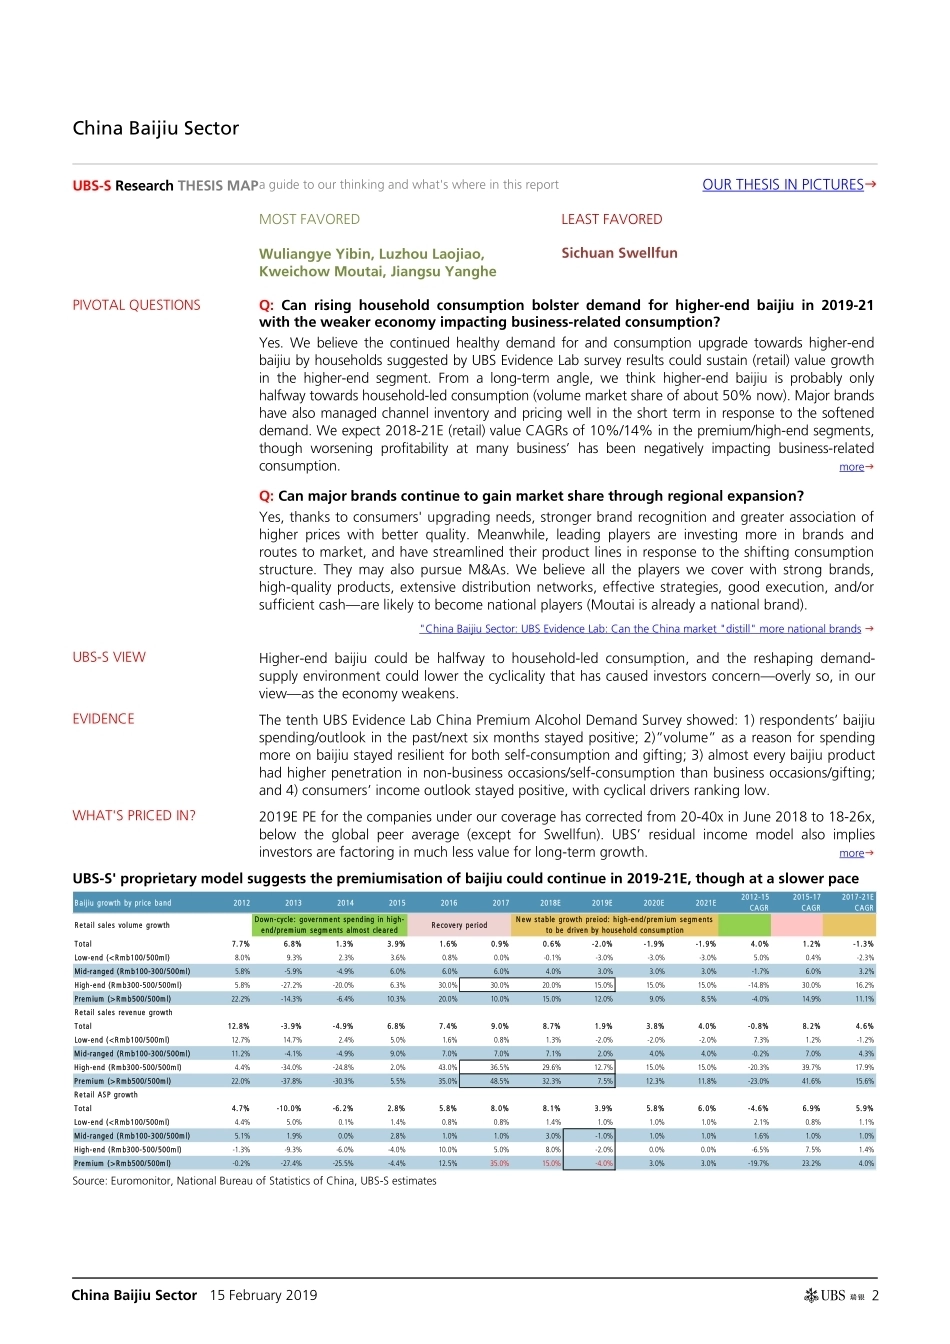
www.ubssecurities.com This report has been prepared by UBS Securities Co. Limited. ANALYST CERTIFICATION AND REQUIRED DISCLOSURES BEGIN ON PAGE 31. UBS does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. abc Global Research 15 February 2019 China Baijiu Sector UBS Evidence Lab inside: only halfway to household-led consumption Positive read-through for household demand for higher-end baijiu We leverage a UBS Evidence Lab China Premium Alcohol Demand Survey covering about 1,000 affluent alcohol consumers in first- and second-tier cities to gauge households’ purchasing power and buying behaviour in higher-end baijiu. The survey’s tenth bi-annual iteration (December 2018) suggested continued robust demand for and premiumisation towards higher-end baijiu by households in the past/next six months on stable income growth. But the sector’s value growth has been moderating, due to the impact of the weaker economy on business-related consumption. The survey results add to our confidence that: 1) household-led premiumisation could bolster sector value growth in the short term; and 2) the sector is only halfway towards household-led consumption in the longer term. We therefore believe long-term value is emerging in leading baijiu players, as 2019E PE has trended down to 18-24x on lingering concerns about higher-end baijiu’s cyclicality, which we consider overdone. UBS‘ proprietary model suggests a 10%+ value CAGR for higher-end baijiu UBS’ proprietary baijiu model suggests 2018-21E value CAGRs of 10%/14% in the premium/high-end segments, with 2019 likely a year of negative (retail) price growth after multiple years of recovery since 2015. Resilient value growth in the higher-end segment could be backed by households’ continuing to trade up, given affluent consumers’ income growth is less affected by the slowing economy, their rising health consciousness, and the still-low penetration rate of higher-end baijiu. Meanwhile, leading baijiu players’ more rational pricing strategies and healthier channel inventories reduce the possibility of sell-in volatility like that in 2013-14. In 2019, premium baijiu could have higher earnings growth visibility than high-end baijiu. Baijiu market could brew more national brands over the next decade With higher-end baijiu’s consumption structure shifting towards households, leading baijiu players have unveiled strategies to become national brands since 2016-17. They are based on building and optimising routes-to-market nationwide and investing more in brand equity and consumer cultivation. We expect major brands to enter a stage of steady, structural growth in the next decade, and continue to gain market share. Cyclical impacts on share prices; long-term value emerging Order of preference based on risk-reward: Wuliangye, Laojiao, Moutai, Yanghe and Swellfun. Figure 1: Summary valuations Share price Price target Market cap PE (x) EV/EBITDA (x) Net cash/ market cap Dividend yield (%) EPS CAGR (%) ROIC (post tax) (%) (Rmb) Rating (Rmb) (Rmb bn) 2019E 2020E 2019E 2020E 2019E 2019E 2018-20E 2019E 2020E Wuliangye 67.96 Buy 69.60 264 17.9 15.8 10.8 9.2 21% 3.6 12.8 120 176 Luzhou Laojiao 48.86 Buy 54.20 72 18.1 15.7 11.6 9.7 13% 4.0 15.8 63 67 Kweichow Moutai 737.16 Buy 769.00 926 23.7 20.0 15.8 13.0 11% 2.2 17.7 121 134 Yanghe 109.34 Buy 133.90 165 17.6 15.4 11.5 9.9 12% 3.9 14.5 70 81 Swellfun 35.42 Neutral 32.00 17 25.7 22.7 18.9 16.3 4% 1.6 12.5 49 41 Above data as of 14 February 2019. Source: Company data, UBS-S estimates Equities China Distillers & Brewers Brad Chen Analyst S1460516060001 brad-a.chen@ubssecurities.com +86-213-866 8985 Frank Su Associate frank.su@ubssecurities.com +86-213-866 8811 China Baijiu Sector 15 February 2019 abc 2 China Baijiu Sector P2 UBS-S Research THESIS MAP a guide to our thinking and what's where in this report OUR THESIS IN PICTURES MOST FAVORED LEAST FAVORED Wuliangye Yibin, Luzhou Laojiao, Kweichow Moutai, Jiangsu Yanghe Sichuan Swellfun PIVOTAL QUESTIONS Q: Can rising household consumption bolster demand for higher-end baijiu in 2019-21 with the weaker economy impacting business-related consumption? Yes. We believe the continued healthy demand for and consumption upgrade towards higher-end baijiu by households suggested by UBS Evidence Lab survey results could sustain (retail) value growth in the higher-end segment. From a long-term angle, we think higher-end baijiu is probably only halfway towards household-led consumption (volume market share of about 50% now). Major brands have also managed channel inventory and pricing well in the short term in response to the softened demand. We expect 2018-21E (retail) value CAGRs of 10%/14% in the premium/high-end segments, though worsening profitability at ...




发表评论取消回复