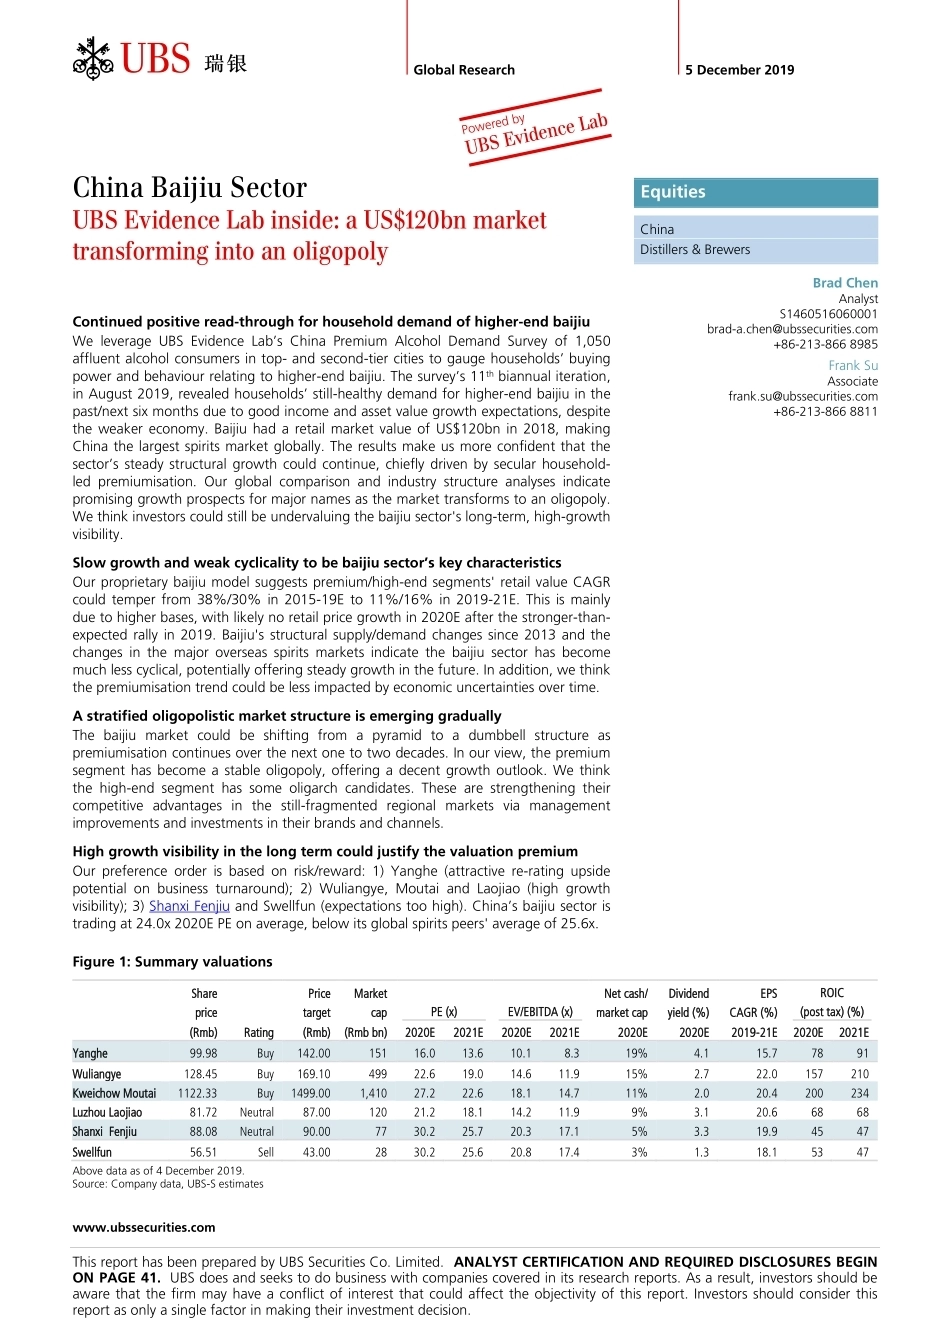
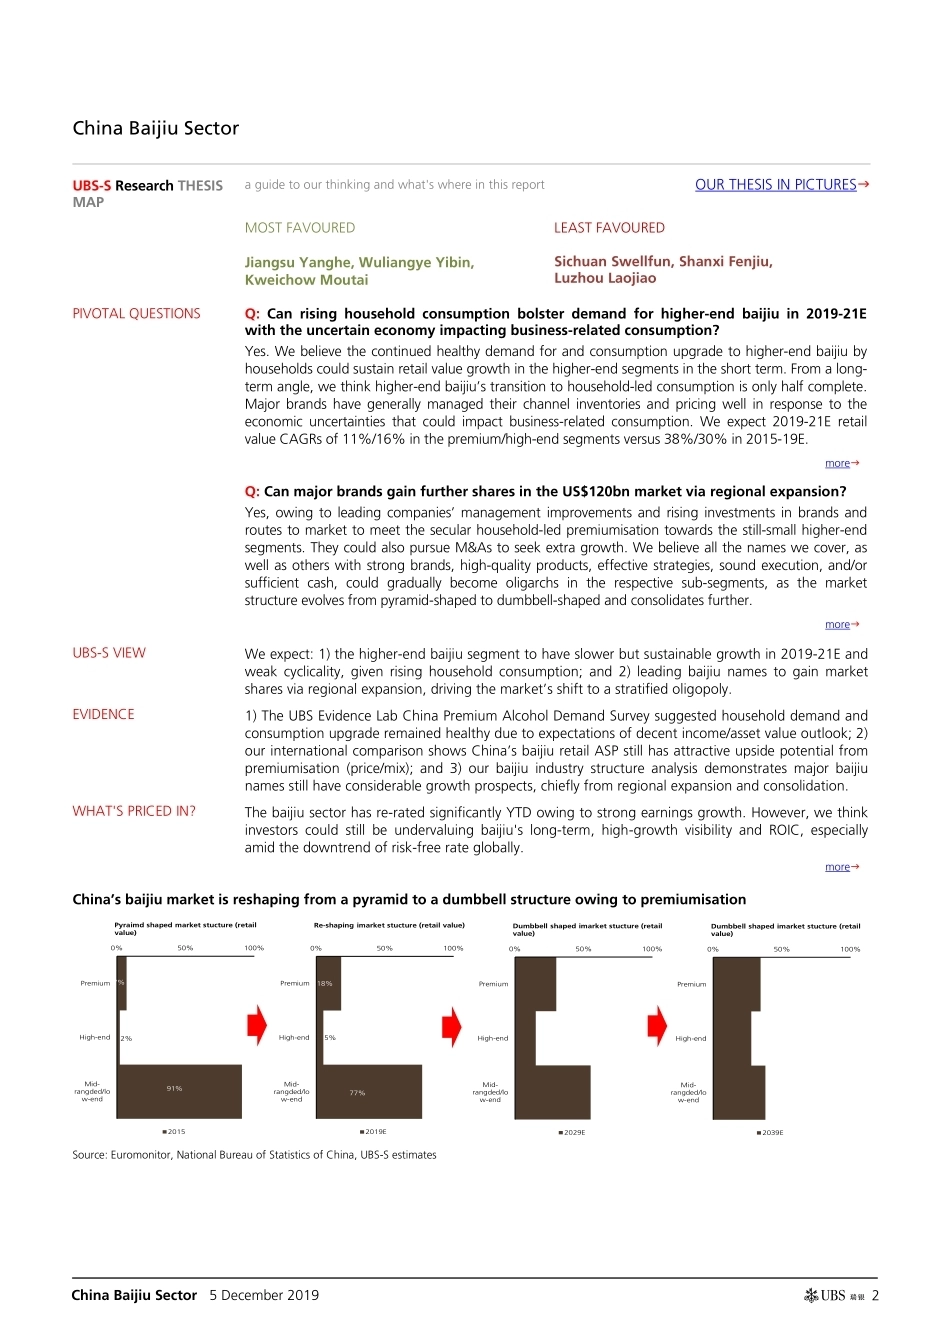
www.ubssecurities.com This report has been prepared by UBS Securities Co. Limited. ANALYST CERTIFICATION AND REQUIRED DISCLOSURES BEGIN ON PAGE 41. UBS does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. abc Global Research 5 December 2019 China Baijiu Sector UBS Evidence Lab inside: a US$120bn market transforming into an oligopoly Continued positive read-through for household demand of higher-end baijiu We leverage UBS Evidence Lab’s China Premium Alcohol Demand Survey of 1,050 affluent alcohol consumers in top- and second-tier cities to gauge households’ buying power and behaviour relating to higher-end baijiu. The survey’s 11th biannual iteration, in August 2019, revealed households’ still-healthy demand for higher-end baijiu in the past/next six months due to good income and asset value growth expectations, despite the weaker economy. Baijiu had a retail market value of US$120bn in 2018, making China the largest spirits market globally. The results make us more confident that the sector’s steady structural growth could continue, chiefly driven by secular household-led premiumisation. Our global comparison and industry structure analyses indicate promising growth prospects for major names as the market transforms to an oligopoly. We think investors could still be undervaluing the baijiu sector's long-term, high-growth visibility. Slow growth and weak cyclicality to be baijiu sector’s key characteristics Our proprietary baijiu model suggests premium/high-end segments' retail value CAGR could temper from 38%/30% in 2015-19E to 11%/16% in 2019-21E. This is mainly due to higher bases, with likely no retail price growth in 2020E after the stronger-than-expected rally in 2019. Baijiu's structural supply/demand changes since 2013 and the changes in the major overseas spirits markets indicate the baijiu sector has become much less cyclical, potentially offering steady growth in the future. In addition, we think the premiumisation trend could be less impacted by economic uncertainties over time. A stratified oligopolistic market structure is emerging gradually The baijiu market could be shifting from a pyramid to a dumbbell structure as premiumisation continues over the next one to two decades. In our view, the premium segment has become a stable oligopoly, offering a decent growth outlook. We think the high-end segment has some oligarch candidates. These are strengthening their competitive advantages in the still-fragmented regional markets via management improvements and investments in their brands and channels. High growth visibility in the long term could justify the valuation premium Our preference order is based on risk/reward: 1) Yanghe (attractive re-rating upside potential on business turnaround); 2) Wuliangye, Moutai and Laojiao (high growth visibility); 3) Shanxi Fenjiu and Swellfun (expectations too high). China’s baijiu sector is trading at 24.0x 2020E PE on average, below its global spirits peers' average of 25.6x. Figure 1: Summary valuations Share price Price target Market cap PE (x) EV/EBITDA (x) Net cash/ market cap Dividend yield (%) EPS CAGR (%) ROIC (post tax) (%) (Rmb) Rating (Rmb) (Rmb bn) 2020E 2021E 2020E 2021E 2020E 2020E 2019-21E 2020E 2021E Yanghe 99.98 Buy 142.00 151 16.0 13.6 10.1 8.3 19% 4.1 15.7 78 91 Wuliangye 128.45 Buy 169.10 499 22.6 19.0 14.6 11.9 15% 2.7 22.0 157 210 Kweichow Moutai 1122.33 Buy 1499.00 1,410 27.2 22.6 18.1 14.7 11% 2.0 20.4 200 234 Luzhou Laojiao 81.72 Neutral 87.00 120 21.2 18.1 14.2 11.9 9% 3.1 20.6 68 68 Shanxi Fenjiu 88.08 Neutral 90.00 77 30.2 25.7 20.3 17.1 5% 3.3 19.9 45 47 Swellfun 56.51 Sell 43.00 28 30.2 25.6 20.8 17.4 3% 1.3 18.1 53 47 Above data as of 4 December 2019. Source: Company data, UBS-S estimates Equities China Distillers & Brewers Brad Chen Analyst S1460516060001 brad-a.chen@ubssecurities.com +86-213-866 8985Frank Su Associate frank.su@ubssecurities.com +86-213-866 8811 China Baijiu Sector 5 December 2019 abc 2 China Baijiu Sector P2 UBS-S Research THESIS MAP a guide to our thinking and what's where in this report OUR THESIS IN PICTURES MOST FAVOURED LEAST FAVOURED Jiangsu Yanghe, Wuliangye Yibin, Kweichow Moutai Sichuan Swellfun, Shanxi Fenjiu, Luzhou Laojiao PIVOTAL QUESTIONS Q: Can rising household consumption bolster demand for higher-end baijiu in 2019-21E with the uncertain economy impacting business-related consumption? Yes. We believe the continued healthy demand for and consumption upgrade to higher-end baijiu by households could sustain retail value growth in the higher-end segments in the short term. From a long-term angle, we think higher-end baijiu’s transition to household-led consumption is only half complete. Major brands have generally managed their channel invento...




发表评论取消回复